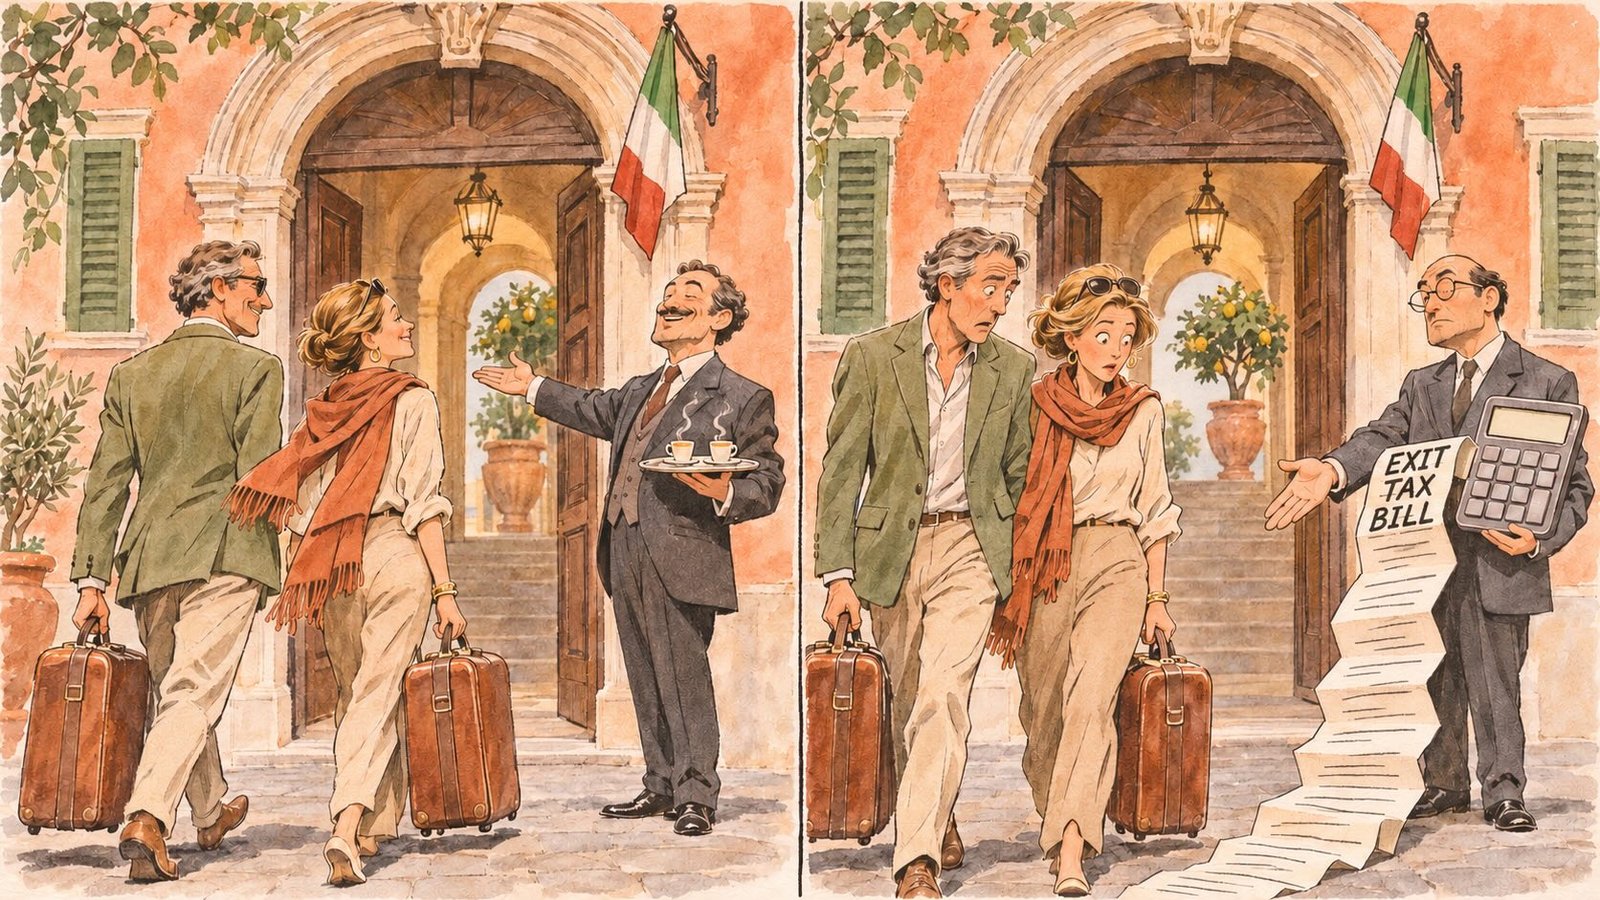
Italy has spent years offering wealthy foreigners a reason to move in. Now it is considering what to charge when they move out. The proposed Italy’s exit tax has unsettled the very people its preferential tax arrangements helped attract, raising an awkward question about the Italian invitation: how much would accepting it eventually cost? The uncomfortable detail is that the bill could concern investments nobody has sold. A portfolio might remain untouched while its owner changes tax residence, yet that departure could trigger a tax calculation. The removal company would not necessarily present the largest invoice.
As of 9 November 2026, the measure remains a proposal in Italy’s draft 2027 budget, rather than an enacted tax. That distinction matters, particularly because the government has already signalled a willingness to reconsider it. On 5 November, Deputy Economy Minister Maurizio Leo told Reuters that Italy would consider changes following criticism from advisers and tax specialists. He did not specify what those changes might involve. For wealthy residents weighing their options, this leaves an unsatisfactory combination: a potentially substantial liability, a proposed start date close at hand and several questions awaiting answers.
The headline figure is 26%, generally applied to unrealised gains on relevant financial assets when someone transfers their tax residence abroad. Two conditions narrow the scope. The person must have been Italian tax resident for at least six of the preceding ten tax years, and the relevant assets must have a combined market value of at least €800,000. The move must also cause Italy to lose its right to tax the gains. This is therefore neither a departure charge for every foreign resident nor a tax confined to foreigners. Italians moving abroad could fall within it too.
The €800,000 threshold concerns asset values, not the size of the profit. Nor does the proposal mean surrendering 26% of an entire portfolio. In a simplified example, relevant shares bought for €1 million and valued at €1.4 million would contain a €400,000 gain. At 26%, that would imply €104,000 of tax before considering any applicable relief or special treatment. The uncomfortable part is liquidity: an increase in a shareholding’s estimated value does not put cash into its owner’s bank account. That distinction becomes particularly awkward when the investment is a private business rather than easily traded shares.
The assets covered also matter. The draft reaches specified financial gains, including those on shareholdings, securities and crypto-assets. Directly owned property falls outside its scope. Describing the proposal simply as a tax on wealth therefore obscures how it would work. A valuable house and a valuable investment portfolio would not receive identical treatment. Even within financial investments, classification could change the outcome. The general 26% figure is not universal either: qualifying government bonds retain preferential treatment. The broad headlines are easy to understand; applying them to somebody’s actual affairs would require considerably more patience.
There is a defensible principle behind taxing gains at departure. Without such a rule, someone might accumulate investment profits while resident in one country, relocate and sell after the original country loses its taxing rights. An exit charge seeks to preserve that country’s claim before the opportunity disappears. Yet the practical design determines whether the result seems proportionate. Valuations, payment deadlines and the treatment of subsequent losses can turn an apparently straightforward principle into a difficult bill. The state sees an accrued gain; the departing investor may see a number that could shrink before anyone buys the asset.
Italy’s draft includes a deferral mechanism, although it offers less immediate comfort than the word suggests. Payment would normally fall due within 180 days of losing tax residence. Moves to qualifying destinations could allow deferral of the balance, but would require a 50% advance payment and a suitable guarantee. The monitoring period would run for five tax years for EU destinations and ten for other eligible countries. Under the proposed rules, liability could disappear for assets retained throughout that period, with excess payments refunded. Even eventual relief, however, could involve years of committed cash and administration.
The greatest uncertainty concerns the interaction with Italy’s special flat-tax regime for qualifying newcomers. That arrangement allows covered foreign income to fall under a fixed annual payment, currently €300,000 for new entrants from 2026. Earlier entrants may have different applicable amounts. For people with very substantial overseas income, the appeal is obvious: a predictable annual figure makes financial planning easier. The exit-tax draft contains no clear coordination between the two systems. Specialists have identified an argument that covered foreign gains deemed realised during the final resident year should fall within the existing flat tax, but that interpretation still needs clarification.
This is where a technical drafting issue becomes a question of confidence. Someone choosing a country for family life, business and investment considers the possible cost of leaving as well as the annual cost of staying. A six-year residence test creates a further tension. In principle, it could encourage some mobile residents to reassess their position before they satisfy it. A measure intended to protect future tax revenue might therefore shorten some stays. That is a possible behavioural response, rather than evidence of an exodus already under way. Alarmed telephone calls to advisers do not constitute a moving census.
There is another reason to resist easy claims about either triumph or catastrophe. Italy’s competition for wealthy residents has distributional consequences, including housing pressures in Milan. It also raises a legitimate question about who benefits from preferential treatment. Yet the economic case for these arrangements remains difficult to measure. The OECD’s 2026 assessment noted that Italian authorities lacked the foreign-income information needed to calculate what participants would otherwise have paid. It also highlighted the difficulty of assessing wider economic gains. Spending by wealthy newcomers is visible; establishing the full fiscal benefit requires more than counting expensive property transactions.
For now, the proposed exit tax has exposed the fragility of selling certainty through a tax incentive. Parliament may revise the rules, and implementing provisions would still need to settle practical details. Clear treatment of existing residents could ease much of the immediate anxiety. The wider lesson is less comfortable for governments competing over internationally mobile fortunes. An attractive annual price can bring people through the door, but their decision also depends on the terms attached to departure. Italy has given prospective residents another document to examine alongside the villa particulars: the cancellation policy.
Post Comment